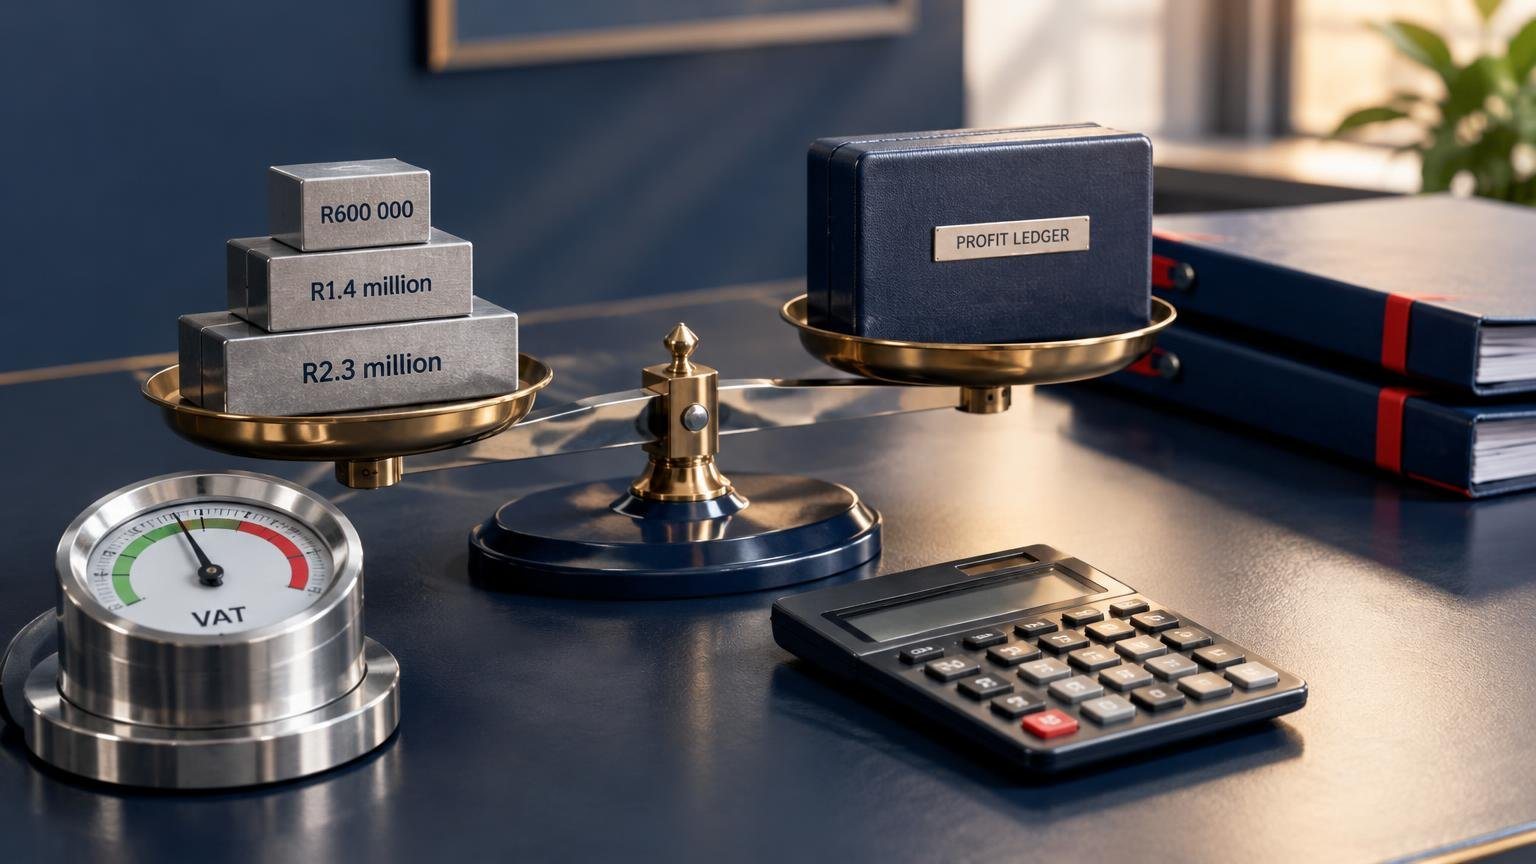
The Turnover Tax qualifying threshold increased to R2.3 million from 1 April 2026. Micro-businesses should reassess eligibility, record-keeping and the effect on VAT and profit margins before choosing the regime.
South Africa’s 2026 tax bills are now before Parliament, with written submissions due by 12:00 on 23 November 2026 and public hearings scheduled for 24 November. SMEs should review the proposals, but must not treat them as enacted law.
SARS Interpretation Note 147 explains when businesses can use the reduced-assessment process for a readily apparent, undisputed tax error instead of lodging a formal objection.
SARS has updated its payment rules to include Investec Bank for Global Minimum Tax foreign payments through SWIFT. Affected multinational groups should review payment controls, PRNs and eFiling access before making cross-border payments.
A new WhatsApp scam impersonating the SARS Commissioner highlights the need for stronger verification, access and payment controls in South African businesses.
SARS has updated the facility code list used in Box 30 of the Goods Declaration to include a new Durban container depot. Importers, customs agents and finance teams should check their master data, shipment records and reconciliation controls before using the new code.
SARS guidance confirms that schools leaving the VAT system must complete key corrections, asset reviews and credit-note processes by the November 2026 VAT period.
SARS published six tariff amendments on 6 November 2026. Importers, vehicle assemblers and fuel-intensive businesses should review costing, customs and diesel-refund controls before the effective dates.
A recent SAICA submission on the 2026 MTBPS highlights the practical cost of compressed consultation periods. South African businesses should distinguish between policy proposals, draft bills and enacted tax rules before changing their accounting or tax processes.
SARS’s proposed Digital VAT Model will eventually connect invoicing, accounting systems and SARS through e-Invoicing, an interoperability framework and e-Reporting. SMEs have time to prepare, but should start by improving the quality and structure of their VAT records.
A recent High Court decision shows how SARS may seek to preserve and realise property linked to unpaid tax while legal proceedings continue. South African finance teams should treat tax-debt monitoring and asset records as core controls.