SARS has issued new guidance explaining how social media influencers and content creators should treat cash, barter benefits, platform income, provisional tax, VAT and business records.
SARS has extended the deadline for certain provisional taxpayers who received an automatic assessment to request a reduced or additional assessment. Businesses and sole proprietors should use the extra time to review their tax information, rather than delay action.
Non-provisional taxpayers who still need to submit their 2026 income tax returns have until 23 October 2026. Businesses should help employees and owner-managers confirm their personal tax obligations, supporting documents and SARS profile details before the deadline.
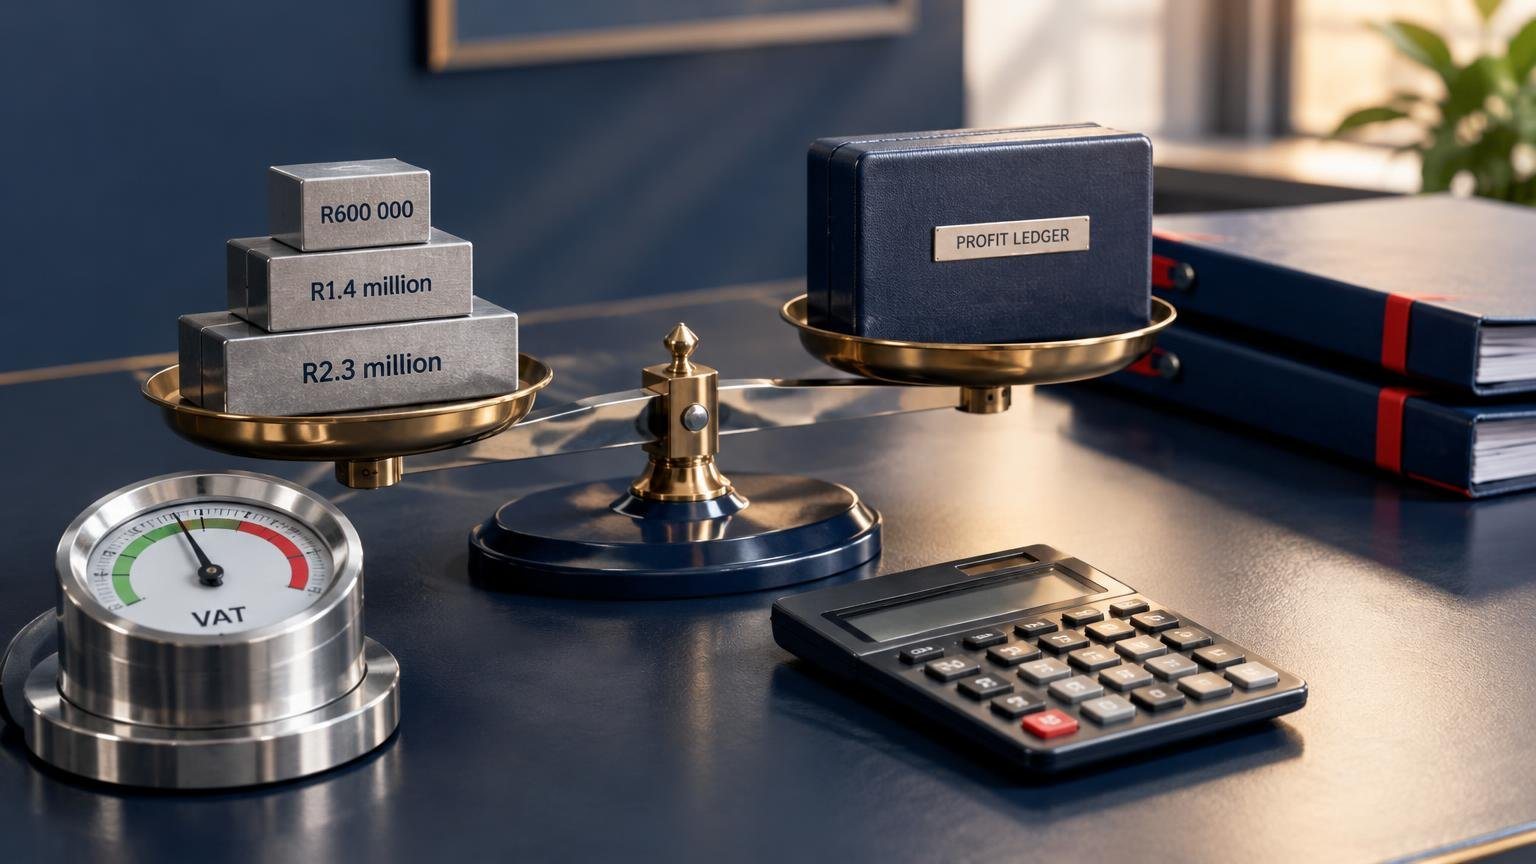
The Turnover Tax qualifying threshold increased to R2.3 million from 1 April 2026. Micro-businesses should reassess eligibility, record-keeping and the effect on VAT and profit margins before choosing the regime.
South Africa’s 2026 tax bills are now before Parliament, with written submissions due by 12:00 on 23 November 2026 and public hearings scheduled for 24 November. SMEs should review the proposals, but must not treat them as enacted law.
SARS has published the explanatory summary of the proposed Tax Administration Laws Amendment Bill, 2026. The proposals could affect provisional tax estimates, PAYE obligations, VAT documentation, tax compliance status and penalty administration. The Bill is not yet law, so businesses should monitor the legislative process and prepare their records without treating the proposals as current requirements.
SARS’s updated 2026 guidance means qualifying micro-businesses with annual turnover of up to R2.3 million should reassess whether Turnover Tax remains suitable for their structure, records and growth plans.
SARS says qualifying micro-businesses can access guided Turnover Tax registration through selected self-service kiosks, giving smaller businesses another route to formalise their tax affairs.
SARS has updated its Guide for Provisional Tax to explain how it may challenge unsupported estimates. Businesses should ensure their provisional tax calculations can be justified and that supporting records can be supplied within 10 business days.
SARS has published requirements for companies seeking to qualify as a REIT, including asset, rental income, leverage, distribution and governance tests. Property groups should assess their financial reporting and tax controls before the rules apply to a new year of assessment.
SAICA has asked National Treasury to clarify how provisional taxpayer status is determined and to provide relief where obligations only become clear after year-end. The proposal is not law, but it highlights practical cash-flow and compliance risks for businesses with irregular income.