Companies with a June financial year-end may have until 31 December 2026 to submit their ITR14 returns. Starting the tax pack early can help finance teams resolve missing records, reconcile balances and reduce last-minute filing risk.
SARS has confirmed an important 2026 filing-season change to the tax treatment of certain assessed losses. Sole traders and individuals with side-business income should review whether the revised Section 20A threshold affects their provisional tax estimates and record-keeping.
SARS’s 2026 Employer Interim Reconciliation period runs until 31 October. Employers should now reconcile payroll data, employee tax numbers and PAYE, UIF and SDL amounts before submitting their EMP501.
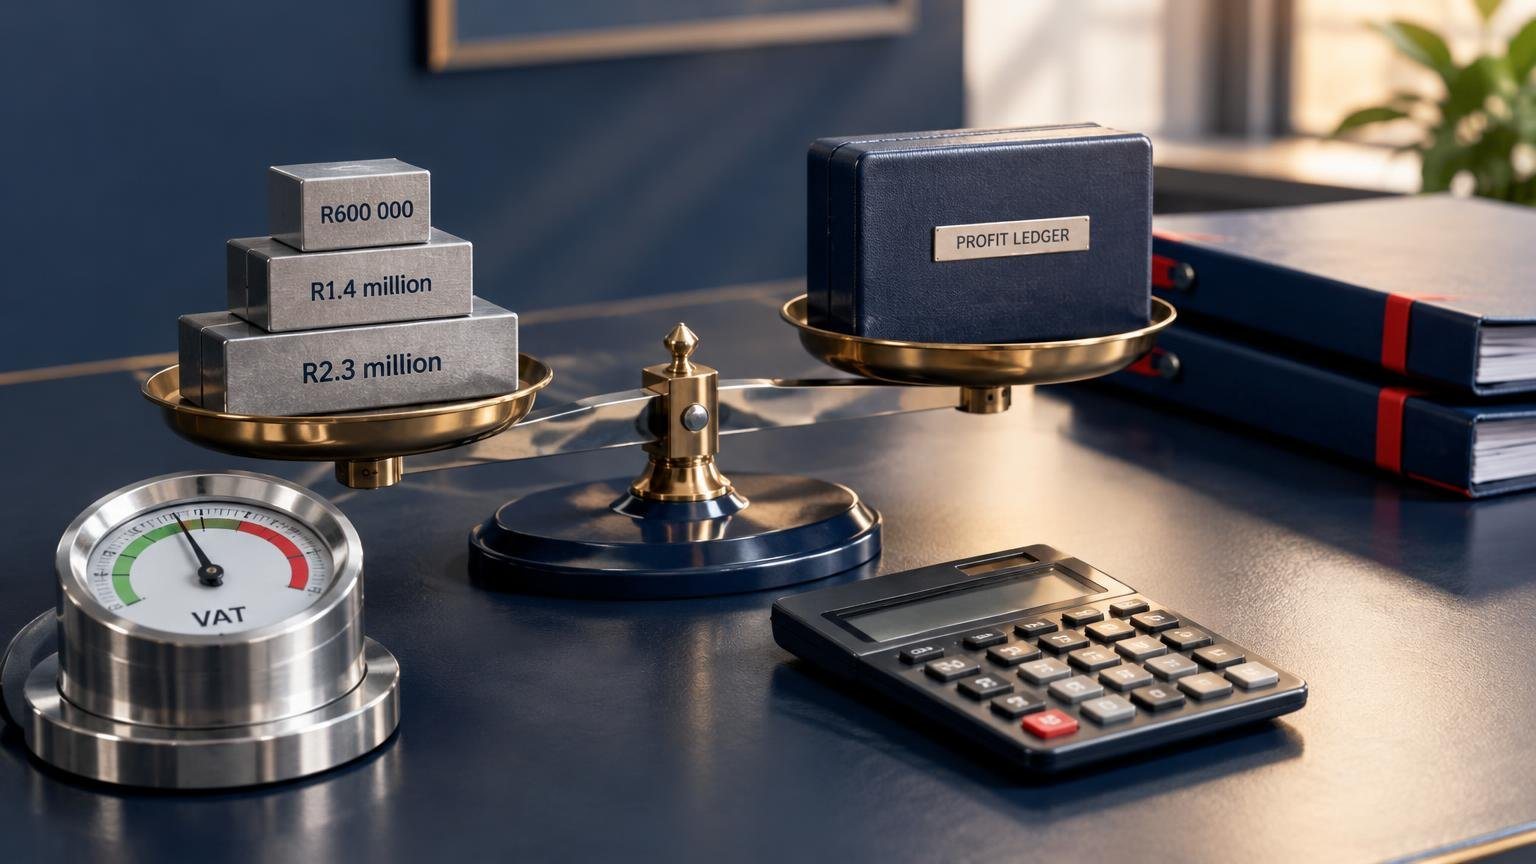
The Turnover Tax qualifying threshold increased to R2.3 million from 1 April 2026. Micro-businesses should reassess eligibility, record-keeping and the effect on VAT and profit margins before choosing the regime.
SARS has published the explanatory summary of the proposed Tax Administration Laws Amendment Bill, 2026. The proposals could affect provisional tax estimates, PAYE obligations, VAT documentation, tax compliance status and penalty administration. The Bill is not yet law, so businesses should monitor the legislative process and prepare their records without treating the proposals as current requirements.
South Africa’s 2026 draft tax bills are moving through parliamentary consideration. They are not law yet, but businesses should monitor the process and assess potential compliance implications.
A practical review of tax invoices, supporting records and VAT201 figures can help South African VAT vendors reduce avoidable errors before submitting their next return.
SARS has published requirements for companies seeking to qualify as a REIT, including asset, rental income, leverage, distribution and governance tests. Property groups should assess their financial reporting and tax controls before the rules apply to a new year of assessment.
South African businesses selling digital services through online platforms should review how VAT responsibilities are allocated between the platform, the underlying supplier and the customer.
A Bill introduced in Parliament on 21 October 2026 proposes raising South Africa’s compulsory VAT registration threshold from R1 million to R2.3 million. SMEs should model the possible impact, but must not treat the proposal as enacted law yet.
South Africa’s finance committees are moving towards finalising the 2026 revised fiscal framework and revenue proposals. SMEs should track the process, but should not treat proposals as enacted tax law.